News
Bayelsa @30 Spending Claims: Setting The Record Straight On Diri Administration’s 2026 Expenditure

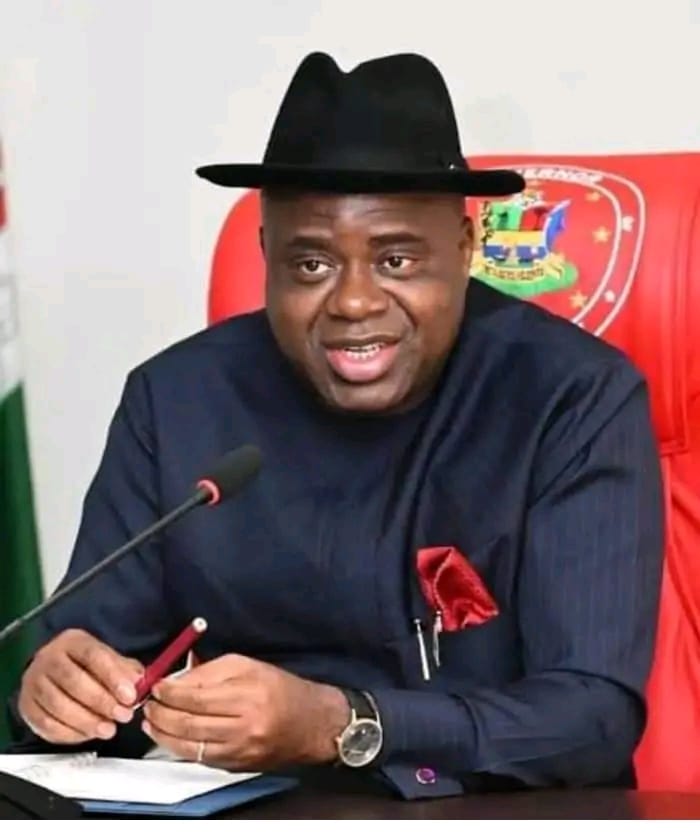
Recent claims alleging that the Bayelsa State Government “spent ₦14.3 billion from Diri’s Governor’s Office in just six months” require careful examination, particularly because the presentation of budget figures can easily create a misleading impression when allocations, releases, commitments and actual expenditure are treated as though they mean the same thing.
The publication attributed to Secrets Reporters attempts to portray the reported expenditure of the General Services Bureau under the Governor’s Office as evidence of excessive spending by the administration of Governor Douye Diri. However, a closer reading of the figures contained in the publication itself shows that the headline and its framing go considerably beyond what the figures, standing alone, can establish.
1: Budget Allocation Is Not the Same as Money Spent by the Governor Personally
The first major problem with the publication is its headline: “₦14.3bn Gone From Diri’s Governor’s Office In Just Six Months.”
That wording gives the impression that Governor Douye Diri personally expended ₦14.3 billion within six months.
2: That conclusion does not necessarily follow from the figures presented.
The General Services Bureau is an administrative structure within government. Expenditure recorded under a government bureau does not automatically mean that the governor personally received, controlled or spent the entire amount.
Government expenditure covers a wide range of statutory, administrative, personnel, operational, welfare, logistical and institutional obligations. Such expenditure may involve salaries, official activities, government-wide services, contracts, programmes, ceremonies, logistics and other responsibilities assigned to the relevant government office.
Therefore, presenting the entire expenditure of an administrative bureau as money “gone from Diri’s Governor’s Office” is potentially sensational and lacks the necessary distinction between institutional expenditure and personal expenditure.
3: The ₦14.33 Billion Figure Needs Context
The publication states that the General Services Bureau had an approved 2026 budget of approximately ₦31.999 billion and that ₦14.333 billion had reportedly been spent by the end of June.
On the face of those figures, ₦14.333 billion represents approximately 44.8 per cent of the annual allocation.
But describing 44.8 per cent expenditure in the first half of the year as inherently excessive is misleading.
ALSO READ: 2027: Ethiope West ADC Boss Rallies Support For Party
Government budgets are annual financial plans. Spending does not necessarily occur in a perfectly linear pattern in which exactly 50 per cent of every budget line must be spent by June 30.
Some obligations are front-loaded. Others are seasonal. Some expenditures may arise from activities scheduled within the first half of the year, while others may be implemented later.
Consequently, the fact that a bureau recorded expenditure below 50 per cent of its annual budget at the halfway point cannot, by itself, establish financial recklessness.
Indeed, based on the publication’s own figures, the bureau had reportedly spent less than half of its annual budget by the end of June, leaving more than half of the annual provision unspent at that point.
The proper question should therefore not simply be, “How much was spent?”
It should be:
What was the expenditure for, was it authorised, was due process followed, and did the expenditure provide value to Bayelsa State?
Those are substantially different questions.
4: The Overhead Figure Also Requires Proper Interpretation
The publication highlights the reported expenditure of ₦3.338 billion out of a ₦5 billion overhead allocation and describes this as one of the fastest-moving components.
While the figure represents about 66.8 per cent of the annual overhead provision, the percentage alone does not prove abuse.
5: Overhead expenditure is fundamentally different from capital expenditure.
Overheads may cover recurrent administrative requirements necessary for the functioning of government institutions. Such obligations can include official operations, logistics, utilities, maintenance, communication, travel, meetings, security-related administration and other approved government activities.
A government cannot operate solely by constructing capital projects. There must also be resources for the machinery that enables government institutions to function.
Therefore, any serious assessment of the ₦3.338 billion should examine the individual payment vouchers, procurement processes, beneficiaries, contracts, approvals and services rendered before declaring the expenditure wasteful or improper.
6: Welfare Allocation Should Not Automatically Be Portrayed as Waste
The publication also draws attention to the reported ₦2.8 billion provision for welfare packages.
Again, the existence of a welfare provision in a government budget does not establish wrongdoing.
Government welfare expenditure can encompass legitimate obligations involving public servants, official programmes, special government responsibilities and other authorised activities.
If there are concerns about the specific beneficiaries or the implementation of the welfare programme, those concerns should be subjected to documentary verification.
What is not appropriate is to transform the existence of a budget line into an allegation of financial impropriety without demonstrating how the money was actually disbursed and whether the expenditure violated any law or financial regulation.
7: Bayelsa @30 Expenditure Must Be Viewed in Its Proper Context
The publication makes considerable emphasis on anniversary and celebration-related allocations, apparently because Bayelsa State marked its 30th anniversary in 2026.
There is nothing inherently suspicious about government making budgetary provisions for a major state anniversary.
Bayelsa’s creation on October 1, 1996, was a significant historical event in the political development of the Niger Delta and the Ijaw people. A 30th anniversary is a major milestone that can legitimately involve cultural programmes, historical documentation, public lectures, exhibitions, awards, commemorative activities, youth and community programmes and other official events.
8: The key issue is not whether money was budgeted for an anniversary.
The key issue is whether the money was properly appropriated and spent for the purposes for which it was approved.
If the expenditure complied with appropriation laws and financial regulations, then the mere existence of an anniversary budget line cannot reasonably be presented as evidence of corruption.
The same principle applies to other government ceremonies and programmes.
9: The Publication Itself Admits That the Figures Do Not Prove Misconduct
Perhaps the most important qualification contained in the publication is its own admission that the figures should not automatically be interpreted as evidence of financial misconduct.
That qualification substantially weakens the sensational character of its headline.
If expenditure figures alone cannot establish misconduct, then it is misleading to present the headline as though ₦14.3 billion has simply disappeared.
10: There is a fundamental difference between:
“₦14.3 billion was reportedly expended by a government bureau”
and
“₦14.3 billion is gone from the Governor’s Office.”
The first is a financial reporting claim that can be verified against government records.
The second carries an entirely different implication and requires evidence showing misuse, diversion, unauthorised payments or disappearance of public funds.
Without such evidence, the latter formulation is unnecessarily inflammatory.
11: The ₦54.87 Billion Governor’s Office Allocation Should Also Be Properly Explained
The publication further points to an approximately ₦54.87 billion allocation for the Governor’s Office and uses that figure to raise questions about spending.
But a government office’s total budget should never automatically be equated with money personally available to the governor.
The Governor’s Office is an institutional structure with numerous administrative responsibilities and personnel.
A total budget allocation can contain multiple subheads and programmes, including recurrent expenditure, personnel costs, overheads and capital expenditure.
Consequently, comparing the total Governor’s Office allocation with isolated expenditure figures without breaking down the underlying components can create a distorted picture.
A responsible financial analysis must distinguish between:
– Budget provision;
– Funds released;
– Actual cash expenditure;
– Commitments;
– Personnel costs;
– Overhead costs;
– Capital expenditure;
– Statutory obligations; and
– Expenditure carried out on behalf of the state government.
Without these distinctions, the public may be left with an impression that the entire allocation is a discretionary fund controlled personally by the governor.
That would be an inaccurate interpretation of how public-sector budgeting works.
12: What Should Be Examined Instead?
Rather than relying primarily on sensational headlines, critics of the administration should demand verifiable documentation.
If there are concerns about the reported expenditure, the appropriate questions include:
1. What specific payments make up the ₦14.333 billion?
2. What were the beneficiaries of those payments?
3. Which expenditure was personnel-related?
4. Which payments were overhead?
5. Which were capital expenditure?
6. Were the expenditures contained in the approved appropriation?
7. Were procurement procedures followed?
8. Were contracts properly awarded?
9. Were goods and services actually delivered?
10. Were payment vouchers properly authorised?
11. Were the expenditures captured in official financial records?
12. Did the relevant oversight institutions raise objections?
13. What value did the expenditures deliver to the people of Bayelsa?
These questions would provide a far more credible assessment than simply calculating the percentage of an annual budget reportedly spent in six months.
13: Governor Douye Diri’s Administration Should Be Judged on Overall Governance
The expenditure debate should also be situated within the broader performance of the Prosperity Administration.
Under Governor Douye Diri, the state government has continued to undertake road infrastructure, electricity, healthcare, education, youth and sports development, urban development and other programmes.
Major infrastructure projects across Bayelsa require significant public expenditure and long-term financial commitments.
Therefore, a fair assessment of government finances should consider both expenditure and outcomes.
If government spends money and delivers functioning infrastructure, services and programmes, the public conversation should focus on the quality, cost and value of those projects rather than simply treating every expenditure as suspicious.
At the same time, transparency remains essential. Government must continue to make relevant financial information available for scrutiny, because public funds belong to the people and every administration must remain accountable.
But accountability should be based on facts, documentary evidence and proper financial interpretation.
14: Sensationalism Must Not Replace Evidence
There is nothing wrong with journalists, civil society organisations, opposition parties or members of the public questioning government expenditure.
Indeed, robust scrutiny is an essential part of democracy.
However, scrutiny becomes less credible when headlines imply conclusions that the supporting figures have not established.
The allegation that “₦14.3bn is gone from Diri’s Governor’s Office” requires much more than citing an expenditure figure from a budget document.
If the ₦14.333 billion was legally appropriated, properly released, duly authorised and legitimately spent on government responsibilities, then it cannot reasonably be described as money that simply “went” from the Governor’s Office.
Conversely, if there is evidence of unauthorised expenditure, inflated contracts, abandoned projects, fictitious beneficiaries or diversion of public funds, such evidence should be presented clearly and subjected to the appropriate investigative and legal processes.
That is the standard expected in responsible public-interest journalism.
15: Conclusion
The figures cited in the publication may warrant scrutiny, but they do not, by themselves, establish financial misconduct by Governor Douye Diri or his administration.
The reported ₦14.333 billion expenditure represents an aggregate figure attributed to a government bureau and should not be casually presented as money personally spent by the Governor, Senator Douye Diri.
Similarly, the approximately ₦54.87 billion allocation for the Governor’s Office should not be interpreted as a personal spending account or the governor or the government.
The real test is whether the expenditures were appropriated, authorised, properly procured, accurately accounted for and converted into legitimate government services and value for the people of Bayelsa State.
Bayelsa at 30 should be a period for sober reflection on the state’s achievements, shortcomings and future direction. Constructive criticism is welcome, but public debate must be driven by facts rather than sensational presentation of budget figures.
Governor Douye Diri’s administration, like every government entrusted with public resources, should remain open to scrutiny. But scrutiny must be fair, evidence-based and properly contextualised.
A budget figure is not automatically evidence of waste. An expenditure figure is not automatically evidence of corruption. And an allocation to the Governor’s Office is not automatically money belonging to the governor personally.
What Bayelsans deserves factual and issue-based reporting as Governor Douye Diri’s administration stands for transparency, accountability and good governance—not conclusions drawn before the underlying financial records have been properly examined.
~ Preye Bagou
Concerned Bayelsan Writes From Yenagoa








Bayelsa @30 Spending Claims: Setting The Record Straight On Diri Administration’s 2026 Expenditure

2027: Ethiope West ADC Boss Rallies Support For Party

Oborevwori: 83 Army Division: Air Defence Regiment In Delta Will Boost Security, Devt

Aguleri-Umuoba Anam Communal Clashes: Soludo Brokers Peace, Sets Up Commission Of Inquiry

ANIAS Congratulates Hon. Christian Aburime On National Excellence Award

Soludo’s CPS, Aburime, Bags Excellence Award In Strategic Communication, Public Service

Who Still Needs The NYSC?

DELSU Releases 2026/2027 UTME Cut-Off Marks, Clinical Science Tops With 77.3

Otefe: Delta State Polytechnic Announces 2026/2027 Post-UTME Screening Dates

Edith Okowa Adopts 50 UNIDEL Students, Pledges Annual N200,000 Support

THE World University Rankings 2027 To Feature Record 2,297 Institutions

Police Arrest One Suspect Over Death Of Delta Education Deputy Director

2nd Term: DELSU Postgraduate Students Purchase Nomination Form For Ivworin